Buying a Fixer-Upper in Atlanta: The Honest Cost Math
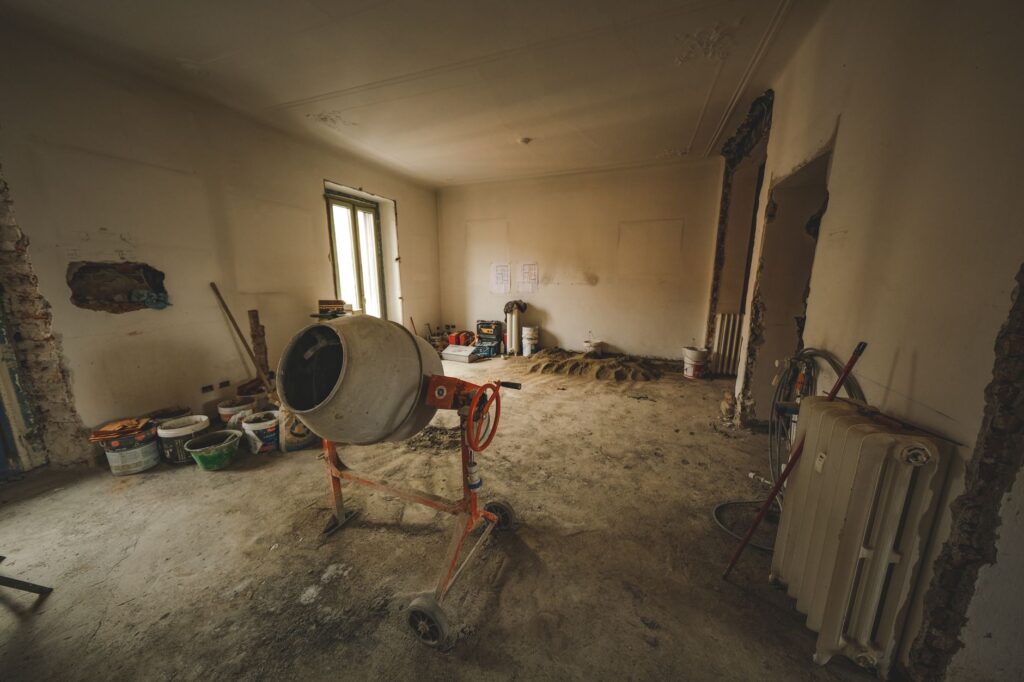
The dollar amounts here are the numbers we see show up in actual closings, not the national averages that show up in lender brochures.
How to Read a Fixer-Upper Budget
- Atlanta kitchen reno $50-125K typical
- Bathroom gut $15-40K
[Review: confirm the bullets above are accurate for Atlanta, then add one sentence on what we tell clients here.]
Renovation Cost Reality in Atlanta
- Permit timelines in Fulton slow in 2026
[Review: confirm the bullets above are accurate for Atlanta, then add one sentence on what we tell clients here.]
Financing Options (203k, HomeStyle)
[Review: confirm the bullets above are accurate for Atlanta, then add one sentence on what we tell clients here.]
What You Can DIY vs Hire
[Review: confirm the bullets above are accurate for Atlanta, then add one sentence on what we tell clients here.]
When a Fixer-Upper Makes Sense
[Review: confirm the bullets above are accurate for Atlanta, then add one sentence on what we tell clients here.]
How Neighborhood Comps Should Drive Your Renovation Ceiling
Before you commit to a fixer-upper budget, you need to know the after-repair value ceiling for the specific block you’re buying on, not the zip code average. In Reynoldstown, a fully renovated 3/2 bungalow typically closes in the $550K to $650K range. Cross into East Atlanta Village and that same footprint might land $40K to $70K lower. Spend past the neighborhood ceiling and you won’t recover it at resale, no matter how sharp the finishes are. We pull active comps and recent closes within a quarter-mile radius before any client makes an offer on a fixer, because that radius is the only number that actually controls your upside.
The practical rule we use: your purchase price plus hard renovation costs should land at or below 80 to 85 percent of the realistic after-repair value for that specific street. If a Morningside bungalow lists at $425K and needs $120K in work, your all-in cost is $545K. If the renovated comps on that block are sitting at $620K, you have margin. If they’re sitting at $560K, you’re already underwater before your first permit is pulled. Inman Park and Candler Park carry enough premium in the renovated market to absorb more aggressive budgets, while some pockets of Cobb and Gwinnett compress that margin significantly. Running this math before the offer, not after the inspection, is what separates a calculated project from an expensive lesson.
The Hidden Line Items Atlanta Fixer-Upper Buyers Routinely Miss
The kitchen and bathroom estimates get most of the attention, but several cost categories show up late in the process and hit hard. Buyers focused on the big renovation numbers often walk into closing without budgeting for these:
- Temporary housing and carrying costs. A full gut renovation on an Atlanta home in the $400K to $600K range typically runs four to eight months with Fulton County permit timelines factored in. Two to three months of overlapping rent and mortgage is a real number, often $4,000 to $8,000 or more depending on your situation.
- Landscaping and site work. Grading, drainage corrections, and tree removal on Atlanta’s hilly, heavily wooded lots run $5,000 to $25,000 and rarely show up in a renovation estimate until the GC walks the exterior.
- Electrical panel upgrades. Older Decatur and Buckhead bungalows frequently have 100-amp panels that won’t support a modern kitchen renovation plus EV charging. Panel upgrades with Atlanta Gas Light coordination often run $3,500 to $7,000.
- Survey and zoning review fees. If you’re planning an addition or ADU, a current survey plus zoning compliance review in Fulton or DeKalb typically adds $1,500 to $3,500 before a single permit application is filed.
- Contingency underspend risk. A 15 to 20 percent contingency sounds conservative on paper, but on homes built before 1970, we routinely see clients exhaust it. Knob-and-tube wiring, cast iron drain lines, and asbestos insulation are standard discoveries in Atlanta’s older intown stock.
The pattern we see most often is buyers who budgeted carefully for the renovation itself and then got surprised by the months in between. Building these line items into your initial underwriting, before you’re emotionally committed to the property, gives you a real picture of what the project actually costs.
Frequently Asked Questions
The earlier you build these numbers into your plan, the fewer surprises at closing. We can pull a personalized estimate for your price range and county before you write an offer, which is far more useful than the generic calculators online. Atlanta costs vary measurably by county, and the standard national estimates are typically off by 10 to 30 percent for our market.
For a typical Atlanta transaction in the $400K to $800K range, this category usually runs $4,000 to $18,000 depending on which county, your specific lender, and the deal structure. The spread is wide because Fulton’s fee math differs from DeKalb, and Cobb differs from both. We can pull a tight estimate once we know your target county and price range.
Some yes, some no. Lender fees and title fees have some flexibility — shopping two or three providers can save real money. Government fees (transfer tax, recording fees) are fixed. Seller concessions toward closing costs are a real lever in this market, especially on listings sitting over 21 days. Buyers leave this lever on the table more often than they should.
Property-related fees vary by county. Fulton has the highest millage rate in the metro but offers a generous homestead exemption for primary residents. DeKalb is mid-range with strong school-zone variation in tax burden. Cobb runs lower on most categories but the math changes again if you’re inside vs. outside Marietta’s city boundaries. We always pull county-specific numbers before the offer goes in.
Build the full cost picture before you commit to a number, then structure the offer with the right combination of price, concessions, and closing-date flexibility. Most buyers focus only on price; the smartest offers in this market use all three levers. The end-of-year tax position, your loan type, and your timing flexibility all play in.
Get pre-approved with a lender who’ll share their actual fee structure (not all do). Pull a real estimate for your target county. Then talk to us about how to structure the offer to minimize what you bring to the table. Book a 15-minute call and we’ll walk through it.
Want a Specific Answer for Your Situation?
These are the typical Atlanta numbers. Your specific lender, property, and county will move them. If you want a personalized estimate, grab 15 minutes on Valerie’s calendar. No sales pitch, just a direct answer. Or send a note through the contact page.
This post reflects current Atlanta market conditions as of May 2026. Tax rules, lending terms, and fees can change. For legal, tax, or compliance questions, consult a qualified Georgia professional.
Featured photo by Francesco Ungaro on Pexels.